

Florida Health Plan Out-of-Pocket Maximums: What Counts?
A health plan's out-of-pocket maximum caps certain costs for covered care, not everything you spend on health insurance. For Florida Marketplace coverage, the 2026 federal limit is $10,600 for an individual and $21,200 for a family, though a plan may set a lower maximum.
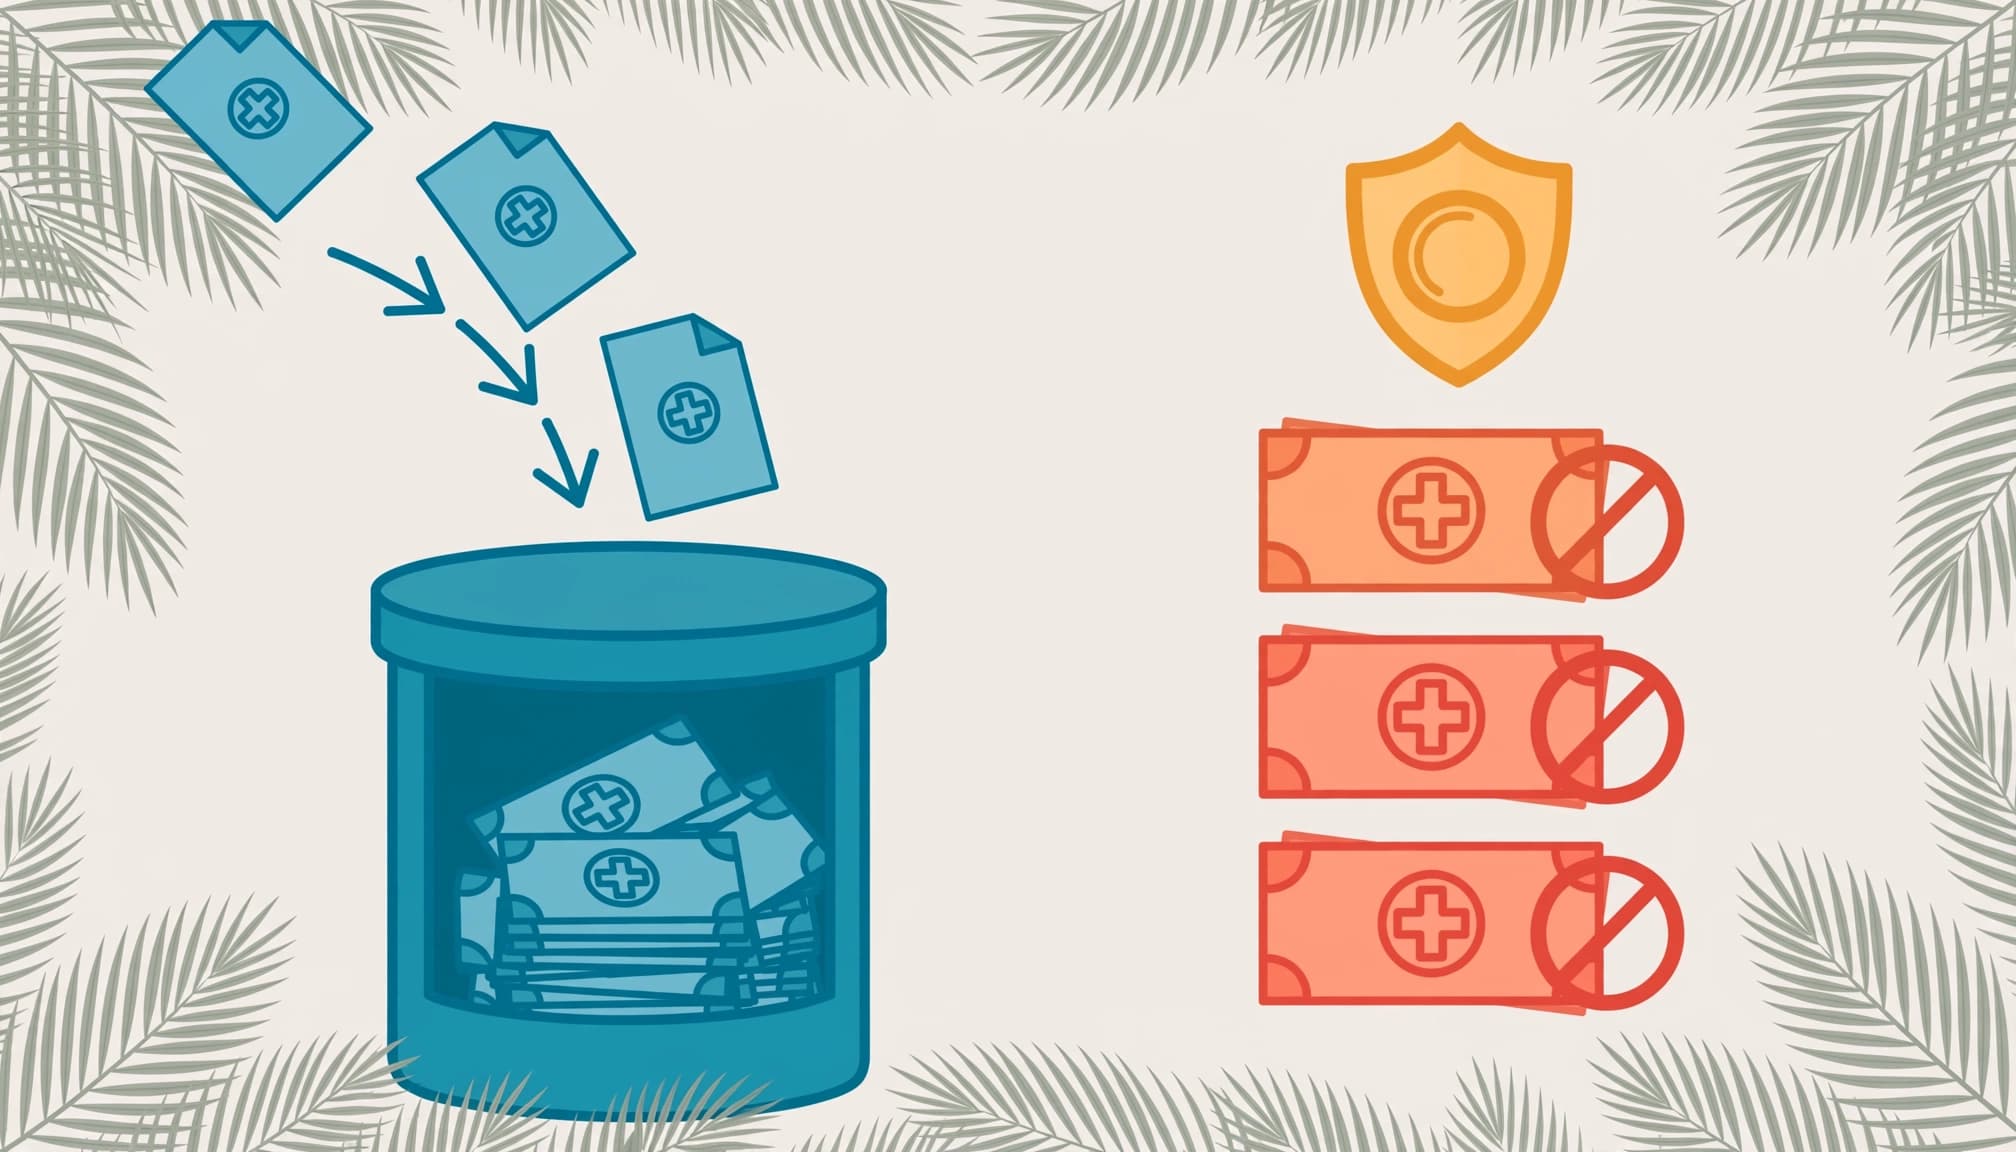
Deductibles, copayments, and coinsurance for covered care generally count. Monthly premiums, services your plan doesn't cover, and many out-of-network expenses generally don't. The plan's benefits and provider network determine how a particular charge is treated.
When comparing Florida ACA Marketplace health plans, look beyond the monthly premium. Start by understanding which payments move you toward the limit.
Key Takeaways
- An out-of-pocket maximum limits what you pay for eligible covered care during a plan year. It isn't a cap on all health-related spending.
- Deductibles, copayments, and coinsurance for covered services generally count when the plan applies them to your limit.
- Premiums, noncovered services, and some out-of-network costs don't count toward the in-network maximum.
- For 2026 Marketplace coverage, the federal maximum is $10,600 for an individual or $21,200 for a family. Plans can have lower limits.
- In family coverage, one person generally won't have to pay more than the self-only limit in eligible cost sharing before the plan's individual protection applies.
- Always read the specific plan's Summary of Benefits and Coverage. Network rules and cost-sharing details vary by plan.
What an out-of-pocket maximum means
An out-of-pocket maximum is the most you pay in eligible cost sharing for covered services during a plan year. After you reach the applicable limit, your plan generally pays 100% of the allowed cost for covered, in-network benefits for the rest of that year.
That limit applies to particular expenses, not every dollar connected to your health. You still owe your monthly premium, and you may owe for care that falls outside the plan's coverage or network rules.
The limit also doesn't mean your insurer pays every provider's full billed charge. For covered in-network care, the plan pays according to its contract and benefits. The maximum limits your share of eligible costs under those terms.
The key question on a bill is whether the plan treats the charge as cost sharing for a covered service, not simply whether you paid it.
HealthCare.gov describes the maximum as a limit on what you spend for covered services. Its guide to total health care costs also separates premiums from costs paid when you use care.
2026 Marketplace limits in Florida
The federal ceiling applies to 2026 ACA Marketplace plans, including plans available in Florida. Under the federal rule, the plan's annual limit can't exceed $10,600 for self-only coverage or $21,200 for family coverage. Some plans set a lower limit, so those figures are ceilings, not guaranteed plan amounts.
Individual and family limits
For an individual plan, the $10,600 limit is the most eligible cost sharing a member may owe in 2026 under the federal cap. For a family plan, eligible expenses for multiple members may accumulate toward a shared family maximum of $21,200.
A plan can have separate deductibles for individuals and families, as well as different copays or coinsurance for specific services. Those amounts shape what you pay along the way, but the federal maximum places a ceiling on eligible cost sharing for covered benefits.
HealthCare.gov lists the 2026 out-of-pocket maximum limits for Marketplace plans. The actual amount in your policy may be below the federal cap.
The individual cap inside family coverage
Family coverage also has an individual protection. One person generally can't be required to pay more than the self-only maximum in eligible cost sharing, even if the family hasn't reached its combined limit.
For example, if one family member has substantial covered medical expenses, that person can reach the individual cap before the rest of the family reaches the family limit. The plan then pays the full allowed cost of that person's covered, in-network benefits for the remainder of the plan year, subject to the plan's rules.
Costs that generally count toward the limit
The maximum usually tracks your share of covered services, rather than the total amount billed by a doctor or facility. Your plan's benefit design determines whether a service has a deductible, copay, coinsurance, or no cost sharing.
Deductibles, copays, and coinsurance
A deductible is the amount you pay for certain covered care before the plan starts sharing those costs. If your plan applies a covered in-network service to the deductible, what you pay generally counts toward the out-of-pocket maximum.
Copayments are fixed amounts for particular services, such as a visit or prescription. A plan may charge a copay before or after you meet the deductible, depending on the service and plan terms. Eligible copays generally count toward the maximum.
Coinsurance is a percentage of a covered charge that you pay, often after meeting the deductible. If you owe coinsurance for an in-network covered service, that amount generally counts as well. For a clear explanation of these cost-sharing terms, see our answers to common health insurance questions.
Covered prescription drugs and other benefits
Your share of covered prescription costs generally counts toward the maximum when the plan applies it as cost sharing. The amount can depend on the drug's tier, pharmacy rules, and whether the prescription is on the plan's formulary.
The same principle applies to other covered benefits. For example, if your plan covers a lab test and charges you a deductible or coinsurance for an in-network test, that eligible payment generally counts. A service covered with no cost sharing won't add to your total, because you paid nothing toward it.
Some Marketplace plans offer reduced deductibles, copays, coinsurance, and maximums through cost-sharing reductions. These savings apply to eligible people enrolled in qualifying Silver plans. Our overview of Florida cost-sharing reductions for Silver plans explains how the assistance changes plan cost sharing.
Costs that generally don't count
It's possible to spend more than the out-of-pocket maximum on health coverage during a year. That happens when you add premiums or expenses the plan excludes from its maximum. A lower limit doesn't eliminate these separate costs.
Premiums and services the plan doesn't cover
Your monthly premium doesn't count toward the out-of-pocket maximum, even if you pay it every month throughout the year. A premium tax credit may lower what you pay for Marketplace coverage, but it doesn't turn premiums into eligible cost sharing.
Costs for services your plan doesn't cover generally don't count either. If a plan excludes a service, or you choose care that isn't a covered benefit, you may owe the full amount without moving closer to the limit. Dental or vision services may have separate coverage and limits rather than counting toward a medical plan's maximum.
This is why the plan with the lowest premium isn't always the lowest-cost choice overall. Compare the monthly payment alongside deductibles, copays, coinsurance, and the maximum. For more context, see how to compare premiums and out-of-pocket costs.
Out-of-network care and balance bills
Out-of-network expenses usually don't count toward a plan's in-network maximum. Some plans cover certain out-of-network services but apply a separate deductible or limit. Others provide little or no coverage outside the network, except for circumstances described in the policy.
Even when an out-of-network service has coverage, you may owe more than the plan's allowed amount. A balance bill is the difference between a provider's billed charge and the amount the plan recognizes. That amount generally doesn't count toward the in-network maximum.
HealthCare.gov's glossary defines out-of-network coinsurance as the share you pay for covered services from a provider without a contract with your insurer. The exact cost and whether any of it counts depend on the plan and the service.
Why network rules and plan terms matter
Two plans can advertise similar maximums while treating everyday expenses differently. One may charge a copay for a specialist visit, while another applies the visit to a deductible first. Their provider networks, drug lists, and out-of-network benefits may also differ.
In-network and out-of-network aren't interchangeable
In-network providers have agreements with the insurer. The plan's contracted rates and benefits determine your share for covered care, and eligible cost sharing generally goes toward the in-network maximum.
Out-of-network care follows different rules. A PPO may cover some services outside its network, often with higher member costs, while an HMO or EPO may limit routine non-emergency care to network providers. A plan may set an out-of-network maximum, but that limit is separate and doesn't necessarily protect you from every balance bill.
Read the plan's cost-sharing details
The Summary of Benefits and Coverage shows how a plan handles deductibles, copays, coinsurance, and annual limits. Check whether each service is covered, whether it requires a referral or prior authorization, and whether the provider is in network.
Also look at prescription tiers and the plan's rules for labs, imaging, and specialist care. For Florida shoppers, provider availability can vary by county and plan. The out-of-pocket maximum is useful for comparing plans, but it can't tell you whether your doctors or expected services fit the coverage.
What happens after you reach the maximum?
Once you've paid the plan's applicable out-of-pocket maximum in eligible cost sharing, the plan generally pays 100% of the allowed cost for covered, in-network benefits for the rest of the plan year. You'll still owe premiums and costs for services the plan doesn't cover. Out-of-network care may also remain subject to separate rules.
The plan tracks eligible spending against the limit. Keep your insurer's explanations of benefits and billing records, especially if a claim appears under the wrong provider or service category. An explanation of benefits isn't a bill, but it shows how the insurer processed a claim and what amount it applied to your deductible or maximum.
The limit typically resets when a new plan year begins. If your coverage starts or renews on a calendar-year schedule, eligible spending starts accumulating toward a new annual maximum in January. The contract's plan-year dates determine when your own total resets.
Frequently asked questions
Do premiums count toward the out-of-pocket maximum?
No. Monthly premiums are separate from cost sharing for care and don't count toward the plan's annual maximum. A premium tax credit can reduce the premium, but it doesn't count toward the limit either.
Does the deductible count?
Generally, yes, when you pay toward the deductible for covered services. The plan's rules determine which services are subject to the deductible and which payments it applies to the annual maximum.
Do out-of-network costs count?
Often they don't count toward the in-network limit. A plan may have a separate out-of-network deductible or maximum, but coverage and billing protections vary. Check the plan's network and benefit terms for the service you're considering.
Does the maximum cover every medical bill?
No. It limits eligible cost sharing for covered services under the plan. Premiums, noncovered care, and certain out-of-network charges can remain your responsibility after you reach the limit.
Choose a limit that fits the coverage
An out-of-pocket maximum is a useful measure of financial exposure, but it only applies to eligible expenses under your plan. For 2026 Marketplace coverage, federal rules set ceilings of $10,600 for individual coverage and $21,200 for family coverage. Your plan's actual maximum may be lower.
Before choosing coverage, compare the maximum with the deductible, copays, coinsurance, providers, and prescriptions you expect to use. The limit matters most when you understand what it leaves out.
Recent Posts










